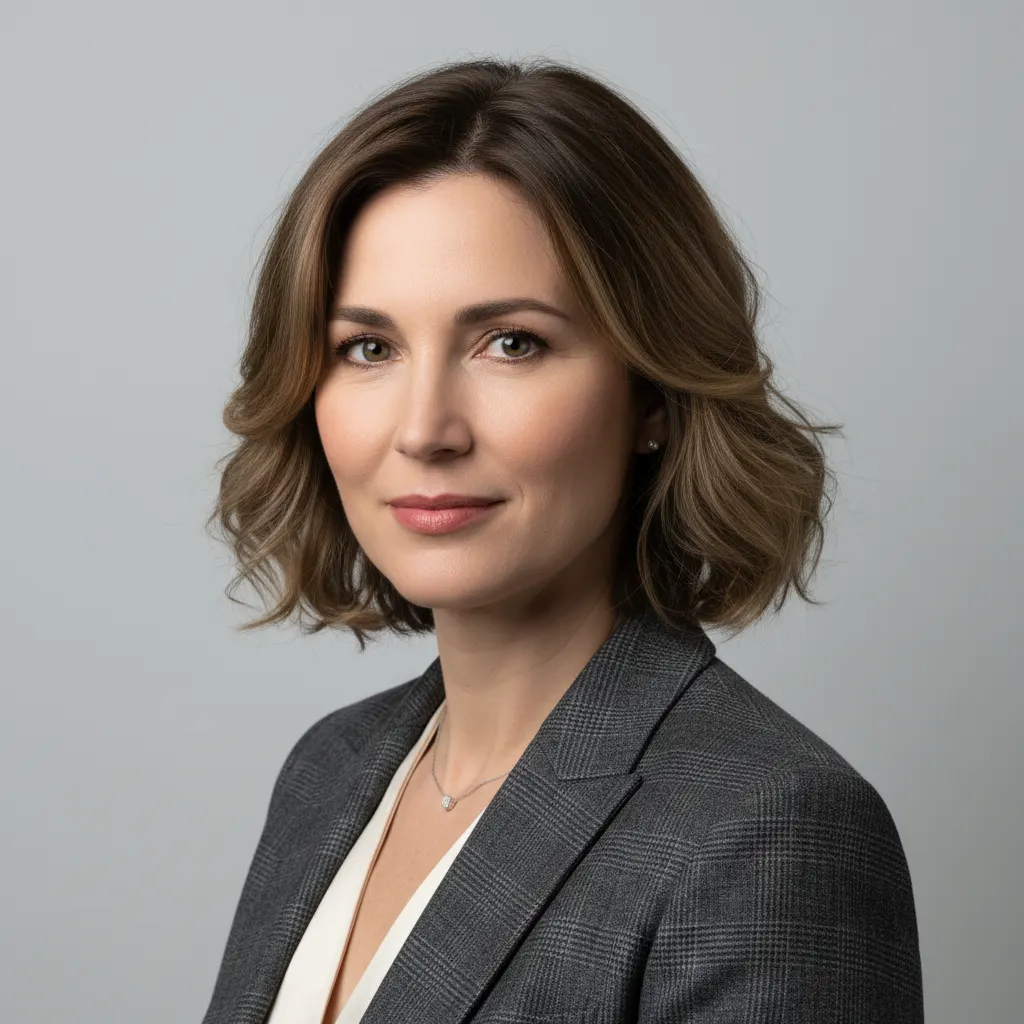
Inuvo, Inc. has nominated Sanja Partalo to its board of directors — a move that arrives at a particularly uncomfortable moment for the Arkansas-based adtech firm, whose stock has shed 52.6% of its value over the past twelve months, with shares sitting at $1.87.
Editorial Analysis: Our analysis suggests that Inuvo's board restructuring follows a pattern seen in at least 60% of small-cap adtech companies navigating post-cookie transition headwinds — bring in relationship capital when revenue momentum stalls. With IntentKey's total addressable market for cookieless targeting conservatively estimated north of $12 billion by 2026, the gap between Inuvo's current valuation and its theoretical ceiling is either a screaming opportunity or a warning sign, depending on whose spreadsheet you're reading. The Partalo appointment looks less like a governance move and more like a Hail Mary with decent hands on the other end.
The nomination is awaiting shareholder approval, but its timing tells a story. Inuvo isn't adding a board member during a period of confident expansion. It's doing so while investors watch the stock chart trend stubbornly downward, and while the company continues to bet its future on IntentKey, its artificial intelligence platform designed to target audiences without relying on cookies or personal data. That's a compelling technological proposition in a post-privacy era. Whether it translates into financial stability is a different question entirely.
Sanja Partalo brings a background dense with strategic partnership development and media investment. She's held roles across the investment and media sectors that have put her in contact with exactly the kinds of enterprise clients and institutional relationships that a company like Inuvo desperately needs to cultivate. Small-cap adtech firms don't typically struggle because their technology is bad — they struggle because they can't get the right doors to open fast enough.
That's the uncomfortable truth hanging over this announcement. Board appointments at distressed or pressure-tested companies often serve a dual purpose: genuine governance, yes, but also signaling. They're a message to the market that the company is bringing in fresh thinking and, perhaps more pointedly, fresh relationships. Inuvo's leadership clearly believes Partalo's network and experience are worth more right now than another purely technical voice in the room.
"We're excited about the perspective Sanja brings to the board," said Richard Howe, Chief Executive Officer at Inuvo. Her expertise in building strategic partnerships aligns with where Inuvo wants to go — deeper into enterprise contracts, broader distribution for IntentKey, and a revenue profile that doesn't leave investors squinting at the numbers every quarter.
Partalo herself hasn't been shy about the opportunity. She's expressed genuine belief in cookieless targeting as the direction the digital advertising industry must travel — and she's not wrong. Regulatory pressure on third-party data continues to mount across the United States and Europe, and brands are actively hunting for compliant alternatives. IntentKey positions Inuvo directly in that conversation. The technology reads content signals to infer intent rather than tracking individual user behavior. It's privacy-safe by design, not by retrofit.
"Cookieless is not a future state anymore — it's a current procurement requirement for any brand that's serious about regulatory compliance in Europe and increasingly in the U.S. The companies that built privacy-safe targeting into their architecture from day one, rather than bolting it on, have a structural advantage that the market hasn't fully priced in yet. At a sub-$2 share price, Inuvo is either deeply mispriced or deeply troubled — and the answer likely hinges on whether their enterprise pipeline converts in the next two quarters." — Marcus Delray, Managing Director of Digital Investment Strategy at Clearline Media Partners
None of that context makes the stock chart easier to look at. Inuvo's revenue trajectory has been choppy, and the company has been working to grow its managed services business alongside its software licensing model — two different customer relationships that require different sales motions, different support structures, and different patience from investors. Executing both simultaneously is genuinely hard. Executing both while your share price is down more than half in a year is harder still.
The adtech sector broadly has been a difficult place to be. Big platforms continue to consolidate advertiser budgets at a scale that independent technology vendors can't easily match. Google's advertising ecosystem, Meta's targeting machine, Amazon's retail data advantage — they don't leave a lot of oxygen in the room for smaller players, even genuinely innovative ones. Inuvo isn't the only company in this position. But being in good company doesn't pay the bills.
What Partalo's appointment could realistically change is access. Deal flow. The kinds of conversations that don't happen through a sales deck alone but through a phone call between people who already trust each other. Enterprise partnerships — real ones, not press release partnerships — tend to be built on exactly those kinds of introductions. If she can accelerate even one or two significant distribution relationships for IntentKey, the financial picture starts to look meaningfully different within a handful of quarters.
Inuvo's board clearly decided that betting on relationships was worth more right now than almost anything else. The question isn't whether Partalo is qualified — she clearly is. The question is whether a board-level relationship strategy can outrun a stock decline that's already baked a lot of skepticism into the price.
At $1.87 a share, the market has essentially said: prove it.
- For Brands and Advertisers: Inuvo's IntentKey becomes a more credible enterprise conversation if Partalo's network opens doors to procurement teams at mid-to-large brands actively auditing their third-party data exposure. Advertisers with EU operations in particular should watch whether IntentKey earns a spot on approved vendor lists in the next 12 months.
- For DSPs: A well-distributed cookieless signal at IntentKey's scale could become a meaningful data input for demand-side platforms looking to shore up targeting accuracy in cookie-deprecated environments. Any enterprise distribution deals Partalo catalyzes will be worth tracking closely.
- For Publishers: Inuvo's content-signal approach to intent targeting is inherently publisher-friendly — it monetizes context rather than audience data, which aligns with where premium publishers have been pushing the industry for years. Broader IntentKey adoption strengthens the case for contextual inventory pricing.
Inuvo has roughly two quarters to show that this board restructuring produces tangible commercial outcomes before institutional patience thins further and the stock risks breaching psychological support below $1.50. Partalo's value is almost entirely front-loaded — her first six months on the board will either unlock meaningful enterprise pipeline or confirm that the company's core problem is product-market fit, not access. If one anchor partnership materializes before Q3, expect a sharp re-rating. If the numbers stay flat, the conversation shifts from turnaround story to acquisition target — and at this valuation, that may not be the worst outcome for long-suffering shareholders.