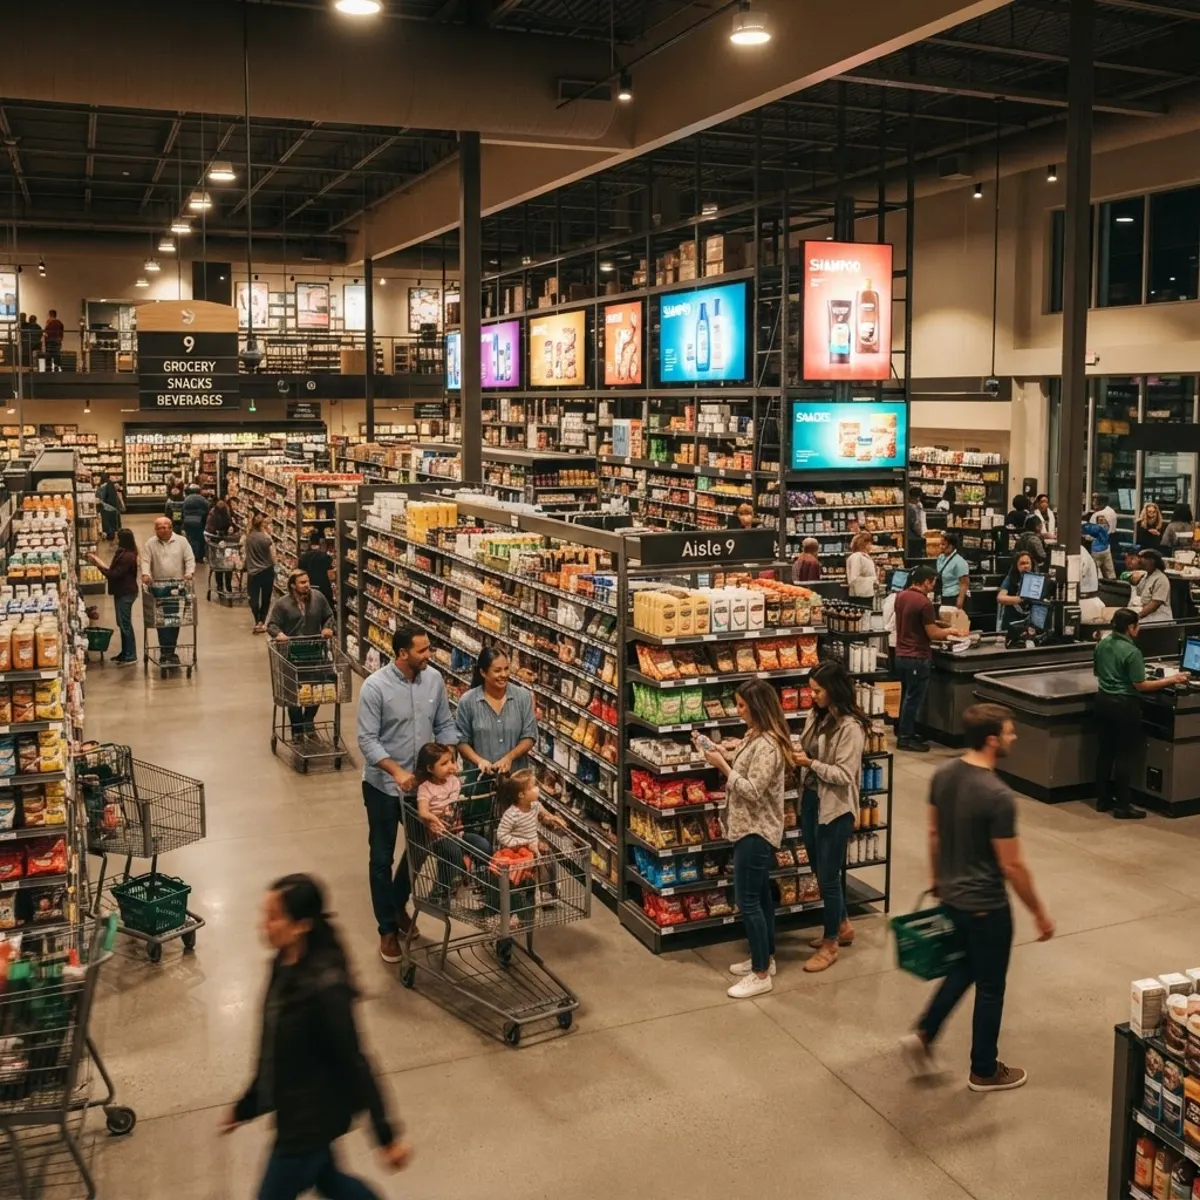
Retail media is no longer confined to the digital shelf, as major retailers aggressively move to capture the lucrative CTV advertising market. Walmart's recent integration with Vibe.co marks a pivotal shift in this trajectory, pulling the retail giant further into the heart of the streaming living room. By bringing Vibe.co's streamlined, self-serve CTV platform into the fold, Walmart isn't just selling ad space; it's attempting to bridge the gap between high-intent retail data and the premium, brand-building environment of television. It's an ambitious play to prove that a viewer watching a procedural drama can be just as targetable as a shopper searching for dish soap.
AdWire estimates that retail media's expansion into CTV will redirect upward of $4.2 billion in traditional broadcast budgets by 2026, with Walmart-affiliated inventory positioned to capture as much as 18% of that reallocation. The velocity of this shift is being driven less by advertiser demand than by retailer urgency - the margins on physical goods are thin, and proprietary ad revenue is becoming a structural necessity, not a growth bonus. Walmart's move with Vibe.co is less a product launch and more a push.
Chris Kelly, Head of Ad Sales at Vibe.co, notes that the integration provides a necessary infrastructure for brands that previously felt priced out or overwhelmed by the complexity of CTV. By simplifying the path from audience segmentation to campaign execution, they're democratizing access to inventory that was once guarded by monolithic walled gardens. It's about agility. If a brand wants to align its streaming creative with specific purchasing behaviors identified at Walmart, they can now execute that with far less friction than traditional linear TV buys. This isn't just about putting ads on a screen; it's about making those ads accountable to the bottom line of a balance sheet.
"The self-serve CTV model is doing to retail media what programmatic did to display a decade ago - it's stripping out the middle layers and forcing accountability on every dollar. Walmart's data asset is genuinely differentiated, but the test is whether they can expose it in a way that's operationally clean for a mid-sized brand running lean. Right now, most of these integrations are still built for the Fortune 500. The $10 million advertiser is still largely on the outside looking in." - Rachel Donovan, VP of Programmatic Strategy at Meridian Commerce Group
Let's look at the numbers. Consider a hypothetical brand allocating a $100,000 test budget across legacy linear TV versus this new retail-integrated CTV model. In the legacy scenario, the brand reaches an audience based on broad Nielsen demographics, paying a premium for reach with a nebulous understanding of how many of those viewers actually visited the brand's website- let alone completed a purchase- within a thirty-day window. It's a game of faith. By contrast, the Vibe.co and Walmart integration relies on a closed-loop measurement framework. If the retail media unit price hovers around a $25 CPM, the brand secures 4 million impressions. The real value, however, isn't in the reach- it's in the Attribution signal.
With the Walmart data layer, the brand can identify a 15% conversion lift in store sales among the specific cohort exposed to the CTV ads. That's a measurable ROAS of 3x or 4x that was previously invisible. When you break it down, the disparity is stark. A campaign that looks like a failure on a standard GRP basis- where the cost per reach point is high- suddenly looks like a gold mine when you correlate it against specific retail sales data. It shifts the conversation from "how many eyeballs?" to "how many baskets?" and that is the fundamental shift retailers are banking on to steal share from traditional broadcast budgets.
Despite the promise, there's an uncomfortable tension simmering beneath the surface of this retail media expansion. Advertisers are increasingly concerned about the "tax" of retail media- a scenario where they are forced to spend on the retailer's proprietary ad network simply to ensure their products remain visible or featured on that retailer's shelves. As Walmart and others move deeper into CTV, the risk of data silos increases. Are we building a more efficient ecosystem, or just creating a series of disconnected, walled-off gardens that force brands to duplicate their efforts across five different retailers?
It's a valid fear. If a brand needs to run a Vibe.co campaign for Walmart, another for Target, and another for Kroger, the fragmentation is staggering. The tech might be better, but the management burden is getting heavier. The industry is currently drunk on the promise of retail data, ignoring the reality that most agencies are struggling to reconcile the differing taxonomies and reporting standards across these various partners. It's a mess of spreadsheets and API integrations that threatens to erode the margins brands are trying to protect. For this to work, we need more than just better pipes; we need a degree of standardization that retailers are notoriously reluctant to provide because their proprietary data is their most valuable competitive moat.
There is a growing sense that the next battleground won't be about who has the most viewers, but who has the cleanest, most actionable path to tie a streaming creative to a physical purchase. We are watching a slow-motion collision between the open web and the retail cloud. Retailers have the data, but they lack the heritage of pure-play streaming expertise. Vibe.co provides the expertise, but they need the scale of Walmart's retail footprint to make it a dominant force. It's a marriage of convenience, but it is one that effectively forces the hand of every other major player in the sector to choose between building an in-house ad stack or ceding their inventory to a third-party specialist.
The next twelve months will reveal if this model can scale beyond the largest CPG brands to the mid-market, as the success of these integrations will depend entirely on how easily a brand can toggle between retail environments without breaking their Attribution models. I predict that we'll see a massive wave of M&A activity focused specifically on independent ad-tech middleware providers that can successfully harmonize retail-media data across fragmented, non-competing retailer silos.
- For Brands and Advertisers: The pressure to allocate dedicated budgets to retailer-specific CTV environments is no longer hypothetical. Brands that don't build internal competency around retail media measurement in the next 18 months will find themselves negotiating from a position of ignorance - paying CPMs they can't justify and accepting attribution models they don't fully control.
- For DSPs: The Walmart-Vibe.co structure represents a direct competitive threat. If self-serve retail media CTV platforms commoditize the buying layer, demand-side platforms that haven't embedded retail data partnerships will lose relevance fast, particularly among mid-market CPG advertisers where margin pressure is sharpest.
- For SSPs: Retailers entering CTV inventory ownership changes the supply dynamic considerably. Publishers relying on SSPs to aggregate streaming inventory should expect Walmart Connect and its peers to increasingly route spend through proprietary pipes, bypassing the open market entirely and tightening available premium inventory for everyone else.
- For Agencies: The operational burden of managing fragmented retail media CTV buys across Walmart, Target, Kroger, and others will break traditional agency workflows. Shops that haven't invested in retail media specialists and unified reporting infrastructure will bleed clients to consultancies that have.
Walmart's move with Vibe.co is the clearest signal yet that retail media's center of gravity is shifting from the product listing page to the living room screen - and the remaining major retailers have, at most, 12 months before the gap in CTV capability becomes a genuine competitive liability. Expect Target to accelerate its own streaming inventory strategy through Roundel, likely via an acquisition rather than a build, and watch for Amazon to respond by opening more of its Prime Video inventory to performance-based retail attribution at lower entry thresholds. The brands that treat this moment as a test-and-learn opportunity rather than a budget line item to defer will own the measurement benchmarks that define the category for the next five years.


 Walmart Connect